Rain Instant Pay

- 4.22K Reviews
- 4.7
- Downloads
- 500,000+
Our take on Rain Instant Pay from Appgk
Getting paid before the usual payday can sound like a small convenience, but it can change how you handle an unexpected expense. I approached Rain Instant Pay as a practical money tool rather than something to open every day for entertainment. Its purpose is straightforward: it connects eligible employees with an employer benefits program so they can access earned pay through Rain. That makes it most useful at a very specific moment—when a bill, grocery run, or transport problem arrives before the next regular paycheck.
The app is a free Business app from Rain Technologies Inc, and its Everyone age rating makes it approachable for a broad audience. It has built a strong user base, with more than 500 thousand installs and a 4.7 average from roughly 34 thousand ratings. Those figures suggest that the central idea works for many people, although they do not remove the most important question: whether your employer participates and whether you personally qualify.
Building a money workflow around Rain
Before opening the app, understand the real starting point
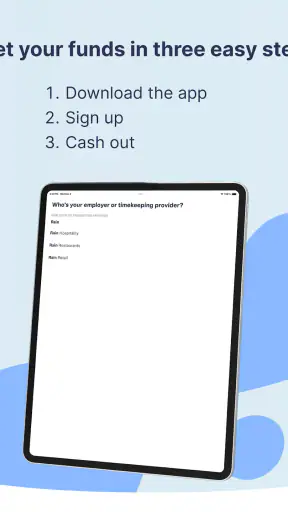
The first thing I would tell a friend is not to treat Rain as a replacement for a bank account or a general budgeting app. It is better understood as an employer-linked benefit. The app can be useful only within that relationship, so the sensible first step is checking whether Rain is available through your workplace and understanding how your employer presents the benefit. If that connection is not in place, installing the app alone will not turn it into a universal early-pay service.
That distinction matters because it changes the workflow. With a normal banking app, I expect to see my existing balance, move money, pay someone, or review transactions. With Rain, I would begin by confirming access, then look at what amount is available and decide whether taking it early solves a real problem. The app belongs in a short-term cash-flow plan, not in the same mental category as savings, a checking account, or a credit card.
Best Parts of Rain Instant Pay
Things to Keep in Mind About Rain Instant Pay
My preferred approach is to identify the expense before requesting anything. If the issue is a utility bill due before payday, I can compare the bill with the amount available and make a deliberate choice. If I simply open the app because money feels tight, the convenience can encourage a cycle of repeatedly pulling pay forward. The best use of instant pay is planned relief, not automatic spending power.
This is also where Rain differs from borrowing products. Accessing earned pay may feel less like taking on a conventional loan, but it still affects the money that reaches me later. I would therefore write down the upcoming payday, the amount needed now, and the amount I expect to have left afterward. That simple pause turns the app from an emergency button into one part of a sustainable cash-flow routine.
News and Features Related to Rain Instant Pay

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Capturing the right information before making a request
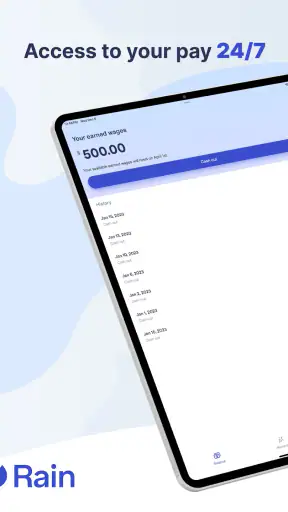
Rain’s usefulness depends on the information presented through the employer connection, so I would review the available balance carefully rather than assuming it equals my final paycheck. Earned-pay access is not the same as receiving all future wages early. The amount shown can guide a decision, but I would still leave room for regular deductions and the expenses that arrive after payday.
A helpful personal system is to keep a small note with three lines: the reason for the request, the amount needed, and the next two unavoidable expenses. This is not a feature I am claiming Rain provides; it is a workflow I would use alongside it. The note prevents a vague feeling of shortage from becoming an unnecessarily large withdrawal and gives me a record to review later.
Don't want to read the full review?
I would also separate urgent needs from optional purchases. A prescription, a necessary commute, or a payment that would otherwise incur a penalty has a clear role in the decision. A spontaneous purchase is different. Rain makes access feel immediate, while the financial consequence is delayed until regular payroll. That timing difference is the main behavioral risk, and recognizing it is more valuable than simply knowing where the request button is.
For someone who receives irregular hours, the available amount may be especially important to inspect. A week with fewer shifts can reduce what is accessible, while a busy week may show more than I actually want to spend. I would use the displayed figure as a ceiling rather than a target. That small rule keeps the app connected to a budget instead of allowing the app’s balance to define the budget.
Screenshots
A repeatable routine for using earned pay responsibly
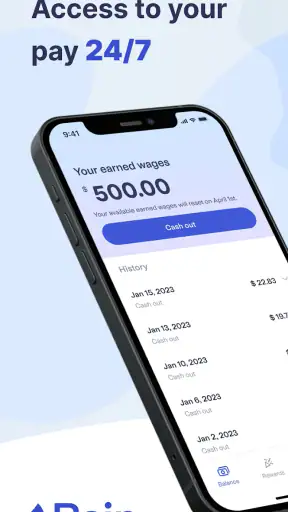
My routine would have four stages. First, I would check the upcoming expense and its due date. Second, I would open Rain and review the amount available through my employer benefit. Third, I would request only what closes the immediate gap. Finally, I would update my personal budget so the next payday is not treated as completely untouched money.
The last stage is easy to skip, but it is the part that makes the process repeatable. If I access pay early and then forget about it, the next paycheck can look unexpectedly small. A calendar reminder on payday or a simple note in a budgeting app can make the adjustment visible. Rain handles the access side; I would use a separate system for the longer view.
Here is a realistic example. Imagine I am working normally, but my car needs an urgent repair before payday. I could compare the repair cost with the amount Rain makes available, request the smallest useful amount, and then reduce nonessential spending until the next payroll deposit. In that situation, the app helps me avoid a more expensive short-term option. If I use it instead for a restaurant meal and then face the repair afterward, the same convenience becomes a weakness.
I would not build a monthly budget around repeated early access unless I had carefully checked my income pattern. A sustainable routine should gradually reduce the need for emergency withdrawals, not make them part of every pay period. Rain can support a bridge across a temporary gap, but it cannot fix expenses that permanently exceed income.
Another practical habit is to review the app at a calm time rather than only during a crisis. I would learn where the available-pay information appears, what confirmation steps are required, and how the request is represented in my own financial records. Doing this before an urgent situation reduces rushed decisions. It also makes it easier to compare Rain with alternatives such as asking a bill provider for an extension, using an existing emergency fund, or waiting for normal payroll.
Where the experience can become less straightforward
The largest limitation is eligibility. Rain is tied to employer benefits, so it is not equally useful for freelancers, people between jobs, or employees whose workplace does not offer the program. Even for an eligible employee, access can depend on employment and payroll information being available to the service. That makes it very different from a general financial app that anyone can open and use independently.
I would also avoid assuming that an available balance represents spendable money with no consequences. The app’s central promise is speed, but speed can reduce reflection. Before confirming a request, I would check the amount twice and consider whether the next paycheck still covers rent, food, transportation, and other fixed commitments. A fast interface is helpful in an emergency, but it can also make an impulsive decision feel harmless.
Another friction point is that Rain should not be my only record of what happened. I would save the confirmation details available in the app and compare them with my payroll information when the next payment arrives. If the amounts look different from what I expected, I would contact the appropriate support or payroll channel rather than making another request to compensate for confusion. Keeping a separate record is especially useful for anyone who manages money across several accounts.
The app is also not the right answer for a continuing debt problem. If I need early access every pay period to cover basic costs, a conversation with an employer, a nonprofit financial counselor, or a detailed spending review may be more appropriate. Rain can ease timing pressure, but it does not increase the total income available over a pay cycle. That is an important boundary, and a responsible review should make it clear.
Compared with a credit card, Rain may be attractive when the goal is to access earned wages rather than add a revolving balance. Compared with a bank overdraft, it may help me avoid relying on a negative account balance. Compared with a savings account, however, it is less protective because it does not create a reserve. And compared with asking for a payroll advance directly, its value is convenience when the employer has already made the benefit available through Rain.
Those comparisons also show when another option is better. I would choose savings for a predictable emergency if I had enough set aside, because that keeps future pay intact. I would prefer a normal banking transfer for money already in my account. I would consider a bill extension before accessing pay if the delay costs nothing and avoids disturbing the rest of the pay cycle. Rain is strongest when timing is the problem and the employer connection is already active.
Small choices that improve the workflow
One non-obvious advantage of thinking in workflows is that the app can become a checkpoint rather than a reflex. I would place it after a quick expense review and before any alternative involving fees or interest. That order helps me compare the real cost of each choice. It also prevents the app from becoming the first response to every uncomfortable balance.
I would set a personal limit below the maximum amount displayed. The exact limit should reflect my fixed bills, not the amount Rain makes accessible. This creates a buffer for payroll deductions and ordinary spending. It is a simple trade-off: I may not solve the entire shortfall immediately, but I reduce the chance of creating a larger problem on payday.
A second useful tactic is to use the app for one clearly defined purpose at a time. If I request money for transportation, I would not mentally blend that amount with grocery money or entertainment. Writing the purpose beside the amount makes later review much easier. This is particularly helpful for people who share household expenses and need to explain why the next paycheck is smaller.
A third is to review the pattern after several pay cycles. I would look for triggers: a particular bill date, a seasonal expense, or a gap between work hours and payment timing. If the same trigger keeps sending me to Rain, I can address the underlying issue by changing a due date, building a small reserve, or adjusting spending earlier in the month. The app then becomes a source of useful feedback about my cash flow rather than a permanent patch.
These habits matter because the convenience is the product’s main strength and its main risk. Rain can reduce the stress of waiting for money that has already been earned, but it can also make future income feel available before it arrives. The right system preserves the convenience while adding a deliberate pause and a record of the decision.
Who should adopt it, and who should skip it
I think Rain is worth considering for an employee whose workplace offers the benefit and who occasionally faces a short gap between an unavoidable expense and payday. It may suit someone who wants a direct, app-based way to manage that timing problem without treating a credit card as the default solution. The free price also makes it easy to explore, provided the user understands that eligibility and responsible repayment through future payroll still matter.
It is less suitable for someone looking for a full budgeting platform, a savings tool, or an account for managing all daily banking. It is also a poor fit for anyone who tends to spend available money simply because it appears on screen. If my income is already insufficient for recurring essentials, I would skip relying on Rain and work on the underlying budget instead.
Rain Technologies Inc has kept the product focused on employer-linked instant pay, and that focus is reflected in its Business classification. The current version is 2.7.1, while the app has been available since February 1, 2020. Its 4.2 thousand written reviews and strong average rating show that many users find the concept useful, but my decision would still depend more on workplace eligibility and personal cash-flow habits than on popularity.
For an eligible employee, I would recommend starting conservatively: identify one genuine need, request the smallest amount that solves it, and record the effect on the next payday. After that first experience, decide whether the workflow reduced stress without encouraging extra spending. That test is more meaningful than downloading the app and immediately treating the available balance as spare cash.
My overall view is positive but carefully limited. Rain Instant Pay can be a practical bridge when earned wages are needed before the normal payroll date, and it is more focused than a general banking app. Its value comes from fitting one specific problem into a broader money routine. I would recommend it to people with access through work who can plan around the next paycheck; I would not present it as a substitute for savings, budgeting, or stable income. Used with that boundary in mind, Rain Instant Pay is a useful safety valve rather than a financial strategy on its own.
Rain Instant Pay FAQ
What is Rain Instant Pay, and how does it work?
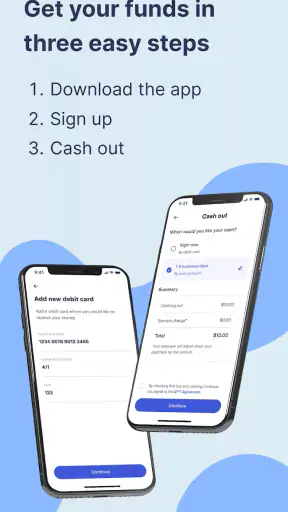
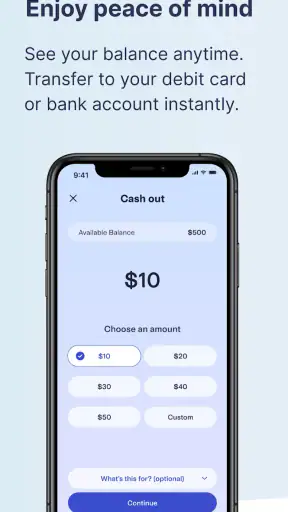
Rain Instant Pay is a financial app designed to give eligible users faster access to part of their earned wages before the regular payday. After creating an account, the app may connect with supported payroll or employment information to estimate available earnings. Users can then request an advance, review the applicable terms, and receive funds through a supported payment method, depending on eligibility and employer participation.
Who can use Rain Instant Pay, and what are the eligibility requirements?
Eligibility depends on several factors, including whether your employer or payroll provider is supported, your employment status, verified income, account history, and the amount of wages already earned. During testing, the app required users to provide accurate personal and employment information for verification. Availability can also vary by location, so installing the app does not guarantee that every user will qualify for an advance.
How quickly are funds delivered through Rain Instant Pay?
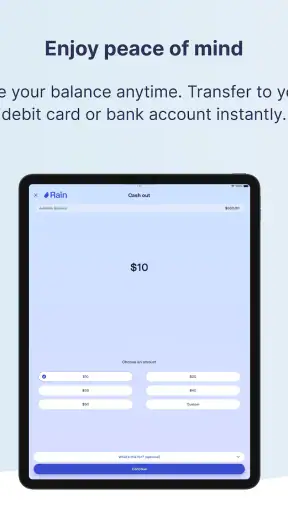
The delivery time depends on the transfer option selected, your bank or debit card provider, verification results, and whether the request is made during business hours. Some transfers may arrive quickly, while standard delivery can take longer. Before confirming a request, users should carefully review the estimated arrival time, transaction status, and any conditions that could delay the payment.
Does Rain Instant Pay charge fees or interest?
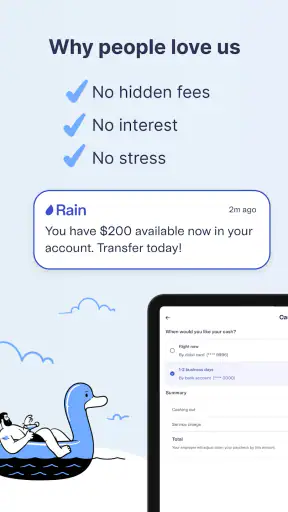
Costs can vary according to the type of advance, transfer speed, account status, and the terms displayed in the app. Some services may offer a no-cost delivery option while charging for faster access, and other features may have separate fees. Always check the final confirmation screen and the provider’s current fee disclosure before accepting a transaction, since pricing and terms may change.
Is Rain Instant Pay safe to use, and what information does it require?
Rain Instant Pay may request sensitive details such as your name, contact information, identity data, employment information, bank account, or debit card details in order to verify eligibility and deliver funds. Use the official app store listing, create a strong password, and enable available security protections. You should also read the privacy policy and understand how financial and personal information is collected, stored, and shared.